How to Manage Rent Increases Without Sacrificing Your Grocery Budget
Marcus Thorne
Senior Loan Analyst · Updated October 2026
Marcus Thorne
Senior Loan Analyst · Updated October 2026
Imagine opening your mailbox in early 2026 to find a notice that your monthly rent is increasing by $250. For many renters, this sudden shift feels like a direct assault on the most essential part of their survival: the grocery budget. When housing costs climb, it is often the food basket that takes the first and hardest hit, leading to a cycle of nutritional compromise or increased debt.
In 2026, economic volatility means that inflation in both the real estate sector and the consumer goods market can move simultaneously. For example, if your rent increases by just 5% on a $2,000 lease, you are looking at an additional $100 every month, which translates to over $1,200 annually. When combined with food inflation rates that may fluctuate between 3% and 7% depending on supply chain stability, the squeeze on your disposable income becomes very real.
This article is designed to help you navigate this specific financial intersection. We will not suggest you simply stop eating well; instead, we will provide a strategic framework for auditing your expenses, negotiating with landlords, and optimizing your food procurement. By the end of this guide, you should have a clear roadmap for maintaining your nutritional standards while absorbing higher housing costs without falling into high-interest debt traps.
We will explore how to mathematically model these changes, compare different budgeting methodologies, and identify the subtle ways that grocery shopping habits can be adjusted to reclaim lost funds. Our goal is to empower you with actionable intelligence so that a rent hike does not dictate your physical health or your long-term financial stability.
Before you can react to a rent increase, you must understand its true impact on your monthly cash flow. Most people look at the monthly difference—for instance, a $150 jump from $1,850 to $2,000—and assume they just need to find that $150 elsewhere. However, this approach ignores the psychological and long-term effects of reduced liquidity.
To accurately assess your situation, you should perform a Monthly Impact Audit. This involves looking at your total monthly income and determining what percentage of that income is now dedicated to housing. For example:
When evaluating these numbers, remember that a sudden spike in rent often coincides with rising utility costs or insurance premiums. It is wise to look at your total cost of living rather than just the line item for rent. If you find yourself struggling to cover both, it may be time to evaluate if your current living situation remains mathematically viable for 2026's economic climate.
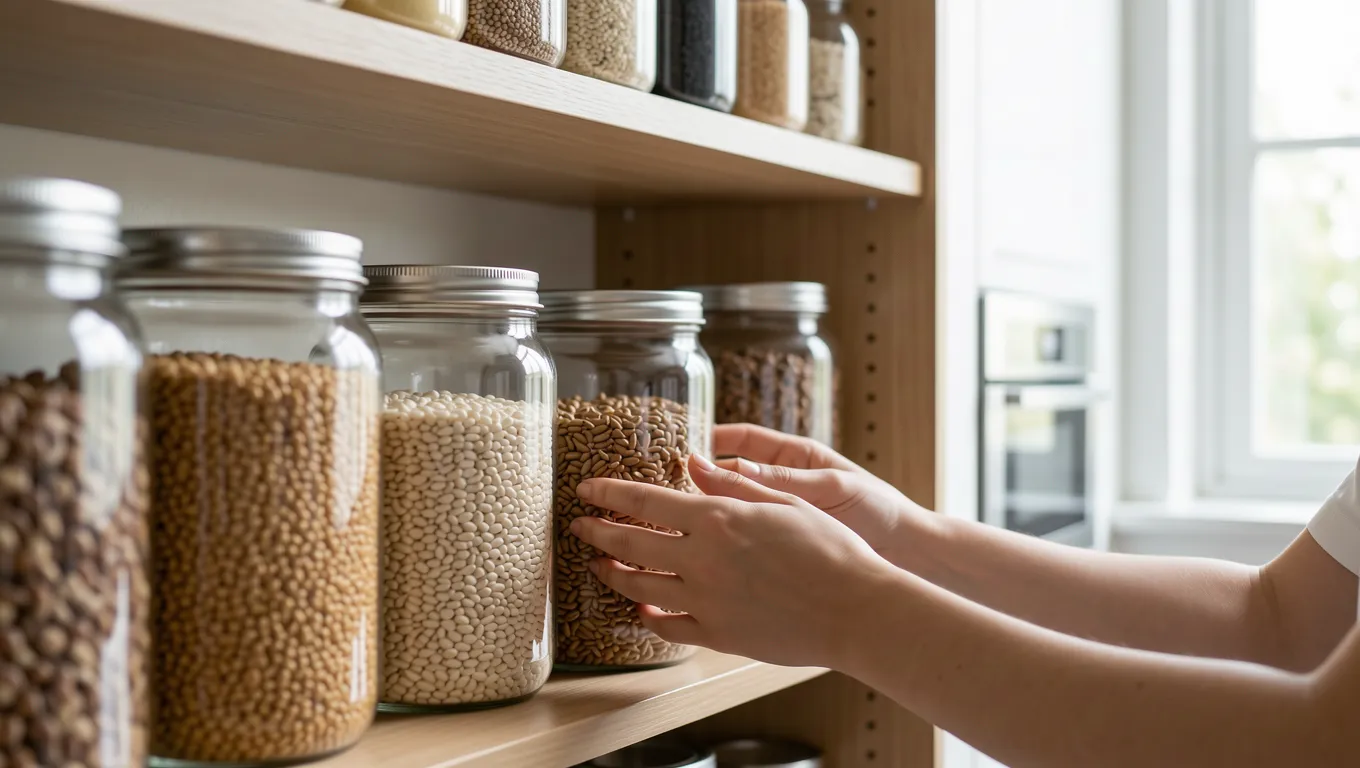
Once the rent increase is a reality, your grocery budget becomes your primary lever for maintaining financial equilibrium. The most effective way to do this is through pantry optimization—shifting how you buy and store food to reduce waste and lower unit costs. This isn't about eating less; it is about buying smarter.
Consider the math of bulk purchasing versus convenience items. Many shoppers fall into the trap of buying pre-cut vegetables or small, single-serving portions. For example:
Another high-impact strategy is the 'Inventory First' method. Before every shopping trip, perform a visual audit of your freezer and pantry. Many households find that they already possess enough ingredients to make three or four meals if they simply look closely. By reducing food waste—which can account for up to 30% of what consumers purchase—you are essentially giving yourself a 'raise' in the form of recovered cash.
When rent goes up, your old budgeting method might no longer work. You may need to choose between two primary strategies: the 50/30/20 rule or Zero-Based Budgeting. Each has distinct trade-offs that depend on how much control you want over every single cent.
The 50/30/20 Rule is a percentage-based method where 50% of your income goes to needs (rent, utilities, groceries), 30% to wants, and 20% to savings or debt. This is excellent for those who want a hands-off approach. However, if your rent increases significantly, that '50%' bucket may expand to 60%, forcing you to take money directly from your 'wants' or 'savings'.
In contrast, Zero-Based Budgeting requires you to assign every single dollar a job until you reach zero. If your rent goes up by $200, you must manually reassign that $200 from other categories like entertainment or dining out. The trade-off is clear:
You do not always have to accept a rent increase as a non-negotiable fact. In many markets, landlords would rather keep a reliable tenant at a slightly lower rate than face the vacancy costs of searching for a new one. Use this leverage by following this decision framework:
The Tenant Negotiation Framework:
If negotiation fails, you must perform a cost-benefit analysis of moving. While moving is often seen as a way to save money, don't forget to factor in the 'hidden costs' like security deposits, movers, application fees, and the time spent packing. Sometimes, staying put and tightening your grocery budget is actually the more economical choice.
The most common mistake people make when their rent increases is attempting to save money by cutting out high-quality nutrition and replacing it with cheap, processed calories. This is a dangerous trap. While pasta and instant noodles are inexpensive in the short term, they often lack the satiety of whole foods, leading to more frequent snacking and higher long-term food costs.
To avoid this, focus on 'The Satiety Ratio.' Ingredients like lentils, beans, eggs, and oats are incredibly cheap per serving and provide high levels of protein and fiber. A single bag of dried lentils can provide enough protein for a week of meals at a fraction of the cost of deli meats or pre-packaged salads.
Warning: Do not fall into the trap of using credit cards to cover grocery gaps during these transitions; this often creates a debt spiral that is much harder to escape than a rent increase.
Expert nuance suggests looking at 'unit price' rather than 'total price.' A large container of Greek yogurt might look expensive, but when calculated per ounce, it is almost always cheaper than the individual cups. Always check the small print on the shelf tags in 2026 to ensure you are actually getting a deal.
Managing a rent increase is about more than just this month; it's about building resilience for the next one. To protect yourself, you should aim to build an 'Inflation Buffer'—a small portion of your income that goes into a high-yield savings account specifically designated for life's inevitable price hikes.
If you find that rent and food are consuming so much of your income that you cannot save anything at all, you might be dealing with a structural debt issue rather than just a temporary squeeze. In such cases, some people look to stabilize their monthly outlays by consolidating high-interest credit card debt through services like Hard Money Loans or other personal finance resources. For example, if someone has $5,000 in debt at 24% APR, moving that to a consolidated loan with an interest rate of 12% could free up the cash flow needed to cover a rent increase without sacrificing food quality.
Ultimately, financial stability is built on visibility. The more you know about where every dollar goes—from your landlord to your local grocer—the less power economic volatility has over your daily life. Stay proactive, stay informed, and remember that small adjustments in the pantry can lead to significant victories in your bank account.
Borrowers weighing this choice often look at bad credit loans and personal loans for bad credit as well.